Comparing developer installment plans, bank mortgages, and full cash settlement requires calculating total outlay with hidden base price markups, matching monthly cash flows to personal liquidity, and verifying contractual clauses before paying a reservation deposit.
Core Financial Models: The Structure of Three Payment Pathways
Purchasing an apartment in the primary real estate market typically revolves around three scenarios: a single lump-sum payment using personal funds, securing a bank mortgage, or utilizing a developer installment program. Each option places a distinct demand on personal capital and demands separate due diligence.
With full upfront payment, the buyer usually secures the maximum discount off the base list price, but immediately removes that liquidity from circulation. A mortgage locks in long-term debt obligations with accrued bank interest, requiring an initial down payment alongside regular monthly installments.
Developer installment schemes distribute payments over a limited construction timeframe, most often until the building is commissioned. Making an objective choice requires comparing not just advertised headline rates, but the full cumulative overpayment, the tranche schedule, and the legal consequences of any missed milestone.
Before choosing a financing program, confirm developer reliability and verify the developer before placing a reservation using a standard audit protocol. verify the developer before placing a reservation.
The Down Payment Trap: Why Low Upfront Cash Does Not Guarantee Value
Marketing campaigns promoting low initial deposits of 5 to 10 percent attract buyers through an accessible entry barrier. However, this minimal start is frequently paired with an inflated nominal price per square meter or a heavy balloon payment at the final stage.
If the baseline property price rises when selecting an installment plan, the buyer encounters a hidden markup that can exceed the total interest cost of a subsidized mortgage. It is critical to request comparative payment schedules from the sales department for both options on the exact same unit.
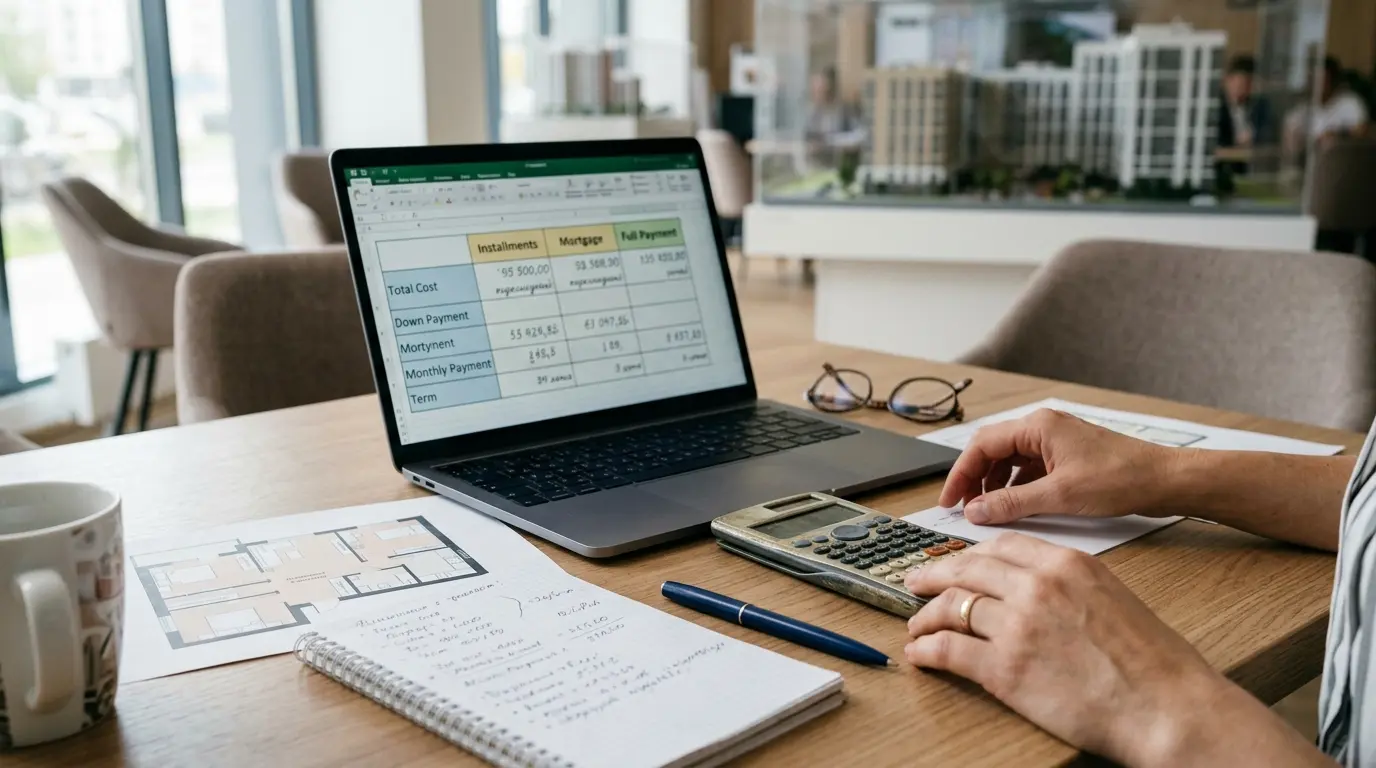
You must compare the final cost of the apartment under full cash settlement against the installment total to identify the exact surcharge paid for deferred financing before signing binding agreements.
Hidden Price Markups and True Total Cost Comparison
Developers frequently maintain tiered price lists: the lowest price applies to 100 percent upfront cash or standard mortgage financing, while zero-interest installment options are calculated from an elevated base price.
To uncover the true overpayment, request an itemized cost calculation for your chosen floor plan across all available payment structures. The difference between the discounted cash price and the total installment outlay reveals the real cost of using developer financing.
When modeling a mortgage pathway, add all mandatory auxiliary expenses to the final sum: life and property insurance, appraisal fees, and bank transaction charges.
When assessing whether price markups are justified for a specific unit, conduct a comparison of layout parameters and liquidity across the residential complex. comparing layout parameters and liquidity.
Monthly Cash Flow Analysis: Preventing Liquidity Gaps
Installment schedules may require equal monthly tranches, quarterly lump sums, or a large balloon payment prior to building completion. Each variation carries specific liquidity risks for personal household budgeting.
A structure with a major final balloon payment requires a verified funding source, such as the sale of secondary property, maturing bank deposits, or transitioning into a mortgage at the handover stage. If market dynamics shift, the buyer faces a severe funding deficit.
Mortgage payments are distributed evenly over a long amortization period, reducing pressure on the monthly budget while increasing total cumulative interest paid to the lender over the loan term.
When evaluating long-term loan obligations, calculate recurring apartment expenses to forecast aggregate outlays after the building is commissioned. calculating the structure of recurring apartment expenses.
Legal and Contractual Restrictions in Developer Schemes
Before selecting a financing route, thoroughly review the draft shared equity construction contract or reservation agreement. Pay close attention to penalty clauses regarding delayed intermediate installments.
Some developers reserve the right to unilaterally terminate the contract or impose heavy fines if an installment payment is delayed beyond a defined grace period. It is equally important to examine assignment terms in case you need to sell the contract rights before completing all payments.
A mortgage creates a bank lien that requires lender consent for any registration actions on the property, whereas an installment purchase keeps developer encumbrances in place until the final tranche is settled.
To avoid forfeiting deposit funds if you adjust your financing method, review the analysis of reservation agreements and refund terms before signing. analysis of reservation agreements and refund terms.
Transitioning from Installments to a Mortgage: Hidden Risks
Many buyers choose an installment plan with the intention of securing a mortgage on the remaining balance near building completion. This strategy introduces several critical decision points that must be planned in advance.
A bank assesses borrower creditworthiness at the moment of loan application, not on the original contract date with the developer. A decline in income, shifts in credit history, or rising macroeconomic interest rates can result in a loan denial.
Additionally, confirm that the construction project remains accredited with partner banks at the transition stage and that the developer agrees to execute a tripartite refinancing agreement for the outstanding debt.
Practical Evaluation Algorithm Before Placing a Reservation
To make an informed decision, build a comparative worksheet for the selected unit tracking three key variables: total aggregate expenditure, initial capital required, and peak monthly budget demand.
Align these figures with the stability of your income streams throughout the full construction timeline. If income is seasonal or project-based, rigid quarterly installment deadlines present higher default risks than predictable mortgage amortization.
Request formal contract templates from the sales office for all evaluated payment options to conduct a legal audit before transferring any refundable or non-refundable reservation fees.
Limitations and suitability
This comparative analysis of financing structures is provided for analytical purposes only and does not constitute individual investment or financial advice. Exact markups, base pricing, and interest rates depend on specific policies of developers and commercial banks.
Installment terms, mortgage lending limits, and upfront cash discounts change based on construction readiness and project documentation. Final legal obligations arise strictly from executed equity participation contracts, mortgage agreements, and their official annexes.
Buyers are responsible for independently verifying current bank eligibility criteria, requesting itemized price sheets from developers, and conducting legal due diligence prior to executing transactions.
| Comparison Metric | 100% Upfront Payment | Bank Mortgage | Developer Installment Plan |
|---|---|---|---|
| Base Unit Price | Minimum with full cash discount | Standard list price or moderate discount | Often increased by 5 to 15 percent |
| Initial Down Payment | 100 percent of purchase price | From 15 to 30 percent | From 10 to 30 percent |
| Payment Horizon | Single lump-sum settlement | Up to 20 or 30 years | Until building commissioning (1 to 3 years) |
| Cash Flow Burden | Maximum one-off capital outlay | Moderate predictable monthly payments | High monthly or quarterly tranches |
| Associated Closing Costs | Minimal | Insurance, property appraisal, bank fees | Minimal until final settlement |
| Liquidity Gap Risk | None after closing | Low with stable ongoing income | High around final balloon payment |
Step-by-Step Due Diligence Checklist for Payment Terms Before Booking
- Request itemized price schedules from the developer for the selected unit across all three payment structures, detailing total outlay.
- Calculate the percentage of hidden markup in the installment plan relative to the 100 percent upfront cash price.
- Calculate the total cost of mortgage financing including mandatory annual insurance and bank closing charges.
- Draft a month-by-month payment calendar across the full construction period and benchmark it against guaranteed income sources.
- Verify the reliability and liquidity of the funding source designated for the final balloon payment under an installment plan.
- Review the draft construction contract for late payment penalties, default interest rates, and unilateral termination clauses.
- Clarify developer rules and consent fees regarding the assignment of contract rights prior to full payment.
- Assess the feasibility and bank eligibility rules for transitioning an outstanding installment balance into a mortgage near project completion.
The true financial benefit of a purchase scheme is determined not by a low initial deposit, but by comparing total net overpayment against the resilience of your personal cash flow throughout the construction horizon.
FAQ
How do you calculate the hidden markup in a zero-interest installment plan?
Hidden markup is calculated as the difference between the apartment price under an installment plan and its discounted price under 100 percent upfront cash payment. Divide this difference by the cash price to determine the effective percentage surcharge for deferred payments.
Is 100 percent cash payment always better than a subsidized mortgage?
Not necessarily. If the return available on conservative capital investments exceeds the effective interest rate of a subsidized mortgage, keeping capital invested and paying mortgage installments can be financially more advantageous than committing all liquidity upfront.
What happens if an intermediate installment payment is delayed?
Consequences depend on the specific contract clauses. Developers typically charge daily late penalties, and prolonged non-payment grants the developer the right to initiate contract termination through judicial or extrajudicial procedures.
Can an apartment under an installment plan be sold via assignment before final payment?
Assignment is possible only with the developer's formal written consent. Contracts may require an administrative assignment fee or mandate that the remaining balance be fully paid prior to state registration of the transfer.
What are the main risks of planning to transition from an installment plan to a mortgage before completion?
The primary risk is a potential mortgage denial by lenders due to changed personal income, a downgraded credit score, or rising market interest rates near project completion, leaving a shortfall for the final balloon payment.
Does the standard mortgage payment calculation include all auxiliary bank expenses?
A standard bank payment schedule reflects only principal and interest. Buyers must budget additional annual outlays for mandatory property and life insurance, independent appraisal reports, and secure settlement services.